An HOA general ledger is the foundation of an association’s financial records. While an HOA board may not have the background or training to make these entries, it should at least understand them. This helps it track financial activity, maintain accurate records, and prevent financial misdeeds.
What is an HOA General Ledger?
An HOA general ledger is the master record consisting of every financial transaction that an association makes. Examples of entries include homeowner dues, vendor bills, and reserve contributions. It uses a standardized double-entry bookkeeping system to track income and expenses.
What is the Importance of a General Ledger for HOAs?
Homeowners associations should maintain a general ledger to establish an audit trail, prepare accurate financial reports, and promote transparency.
- Audit Trail. When tracing financial records and comparing them against invoices, bank statements, and other documents, HOAs and CPAs use the general ledger as the primary reference.
- Basis of Financial Reports. An HOA general ledger serves as the primary repository for all financial transactions. All other financial reports, including the balance sheet and income statement, rely on the general ledger as a data source.
- Transparency. Associations can use the general ledger to prevent fraud and monitor the community’s financial condition. When suspicious financial activity arises, boards can trace transactions and confirm their validity through the general ledger.
What are the Key Components of an HOA General Ledger?
An HOA general ledger has three key components: the chart of accounts, essential columns, and the transaction record. Let’s discuss each one below.
1. HOA Chart of Accounts
The chart of accounts is the standard an association uses to record its entries. It uses numbered titles for assets, liabilities, equity, revenue, and expenses. Every HOA has its own unique chart of accounts.
2. Essential Columns
The essential columns are labeled with the date, account number, reference number, description, debit, credit, and ending balance. These are the details recorded with every entry.
3. Transaction Record
Whenever money moves in or out of the association, the association must update its general ledger. Record changes continuously as financial transactions and operations occur.
What are the Accounting Methods Used for an HOA General Ledger?
When recording transactions in an HOA general ledger, an association must use one of three standard accounting approaches: accrual basis, cash basis, or modified accrual basis. Let’s discuss them below.
1. Accrual Basis of Accounting
The accrual method requires the recording of revenues and expenses when they are incurred. This is the most detailed approach and the only one compliant with Generally Accepted Accounting Principles (GAAP).
2. Cash Basis of Accounting
The cash method records revenues and expenses when money actually changes hands. If revenue is earned but not yet collected, the HOA records no transaction. The HOA records revenue only when it receives the money. It is the simplest approach.
3. Modified Accrual Basis of Accounting
The modified accrual method combines the first two methods. It requires recording revenues when earned and expenses when paid (when money changes hands).
How to Read an HOA General Ledger
To read an HOA general ledger, the board must first understand what each recorded transaction represents. These include:
- Date. This is when the association recorded the transaction or when it occurred, depending on the association’s accounting system.
- Account Number. This is the numerical code assigned to the transaction according to the HOA chart of accounts.
- Description. This describes the vendor or the payment/deposit. For example, when recording revenue from facility rentals, this may show “Clubhouse Rental Income.”
- Reference. This identifies the document or record associated with the transaction. It may include an invoice number, check number, receipt number, or journal entry ID.
- Debit and Credit. These are the amounts recorded on either side of a transaction. Whether a debit or credit increases or decreases an account depends on the account type. For example, a debit generally increases an expense account, while a credit generally increases revenue.
- Ending or Running Balance. This indicates how much is remaining in that specific account line after the recorded entry.
Using the HOA General Ledger to Compare Transactions
From there, the HOA board must review the chart of accounts. This helps confirm the account category is accurate before the board reviews individual entries.
Correctly coding transactions is important. In general, an association maintains two funds: the operating fund and the reserve fund. The board must tag an operating expense accordingly. The same goes for reserve-related transactions. Blending the two can create reporting and tracking problems.
When reviewing the HOA general ledger, scan each transaction for accuracy. Common red flags include unusual vendor names, missing reference numbers, or vague entry descriptions.
After that, the HOA board must check the ledger transaction totals and compare them against financial reports. These include monthly bank statements and reconciliations. If something doesn’t match, the board must investigate further to trace the discrepancy’s source.
Who Should Handle the HOA General Ledger?
Every association has different protocols, but most leave the general ledger to the HOA treasurer or the association’s accountant.
The treasurer oversees the association’s finances. This can include recording transactions in the general ledger and preparing financial reports. That said, because board members are volunteers, the treasurer may lack the accounting or financial background needed to maintain an accurate ledger.
For this reason, many associations choose to hire a Certified Public Accountant (CPA) or bookkeeper. A CPA or professional bookkeeper has the training to track and record financial activity according to the HOA’s accounting method. They are more adept at classifying transactions under the correct titles.
Many communities instead rely on an HOA management company. These companies typically provide accounting and financial management support, including recording general ledgers and preparing financial statements.
HOA General Ledger Example
Let’s consider a scenario involving ABC Homeowners Association. For the month of April, this HOA:
- Receives $4,000 in homeowner dues,
- Pays $1,200 for landscaping, and
- Pays $500 for insurance.
The general ledger could look like this:
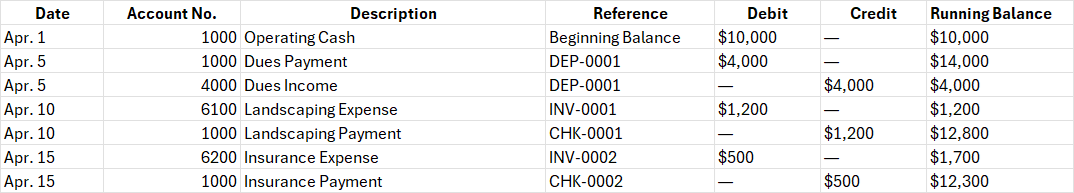
The account number identifies the account in the HOA chart of accounts. The description explains the transaction, while the reference number connects it to the related deposit, invoice, or check.
The debit and credit columns show how the transaction is recorded. Finally, the running balance shows the account’s cumulative balance. Income and expense accounts have their own cumulative balances.
Part of the Job
An HOA general ledger plays an essential role in tracking and confirming financial activity. Board members must learn how to read these entries and use them to inform future decisions.
National Realty Partners is a leading provider of HOA financial management services in Virginia, Maryland, and Washington, DC. We can help your board enforce rules. Call us today at 703-435-3800 or request a proposal online!
RELATED ARTICLES:
- HOA Investment Policy: Protecting Funds And Meeting Fiduciary Duties
- HOA Records Requests In Virginia: What Homeowners Can Inspect
- Preparing For An HOA Audit: A Board’s Guide To Financial Accountability